



Week in Review: AI Fears and Inflation Data Rattle Markets
U.S. stock markets concluded a volatile week with significant losses across the major indices, snapping a multi-month winning streak for some. For the week ending February 27, 2026, the S&P 500 fell 0.81%, the Dow Jones Industrial Average declined 1.62%, and the tech-heavy Nasdaq Composite dropped 1.23%. Small-cap stocks also suffered, with the Russell 2000 losing 1.65% on the week. Meanwhile, international markets fared better, with the MSCI EAFE gaining 0.50% as investors rotated out of U.S. technology stocks and into overseas markets.
The market sentiment was predominantly shaped by a confluence of factors, including mounting concerns over the disruptive potential of artificial intelligence on established business models, renewed uncertainty surrounding global trade tariffs, and hotter-than-expected inflation data which tempered expectations for near-term interest rate cuts from the Federal Reserve. While technology and financial sectors bore the brunt of the sell-off, defensive sectors such as Utilities (+2.53%) and Consumer Staples (+2.59%) demonstrated resilience, attracting investors seeking safe-haven assets amidst the growing market anxiety. The month of February ended on a sour note, with the Nasdaq posting its worst monthly performance since last spring, declining 5.09%, while the S&P 500 fell 1.79% for the month.
Top Stories of the Week
Nvidia's Stellar Earnings Overshadowed by AI Competition
Despite posting record-breaking quarterly revenue of $68.1 billion — up 73% year-over-year — driven by soaring demand for its AI chips, Nvidia (NVDA) saw its stock decline nearly 7% for the week, its sharpest pullback since November. The paradoxical market reaction stemmed from investor anxiety over increasing competition among AI chip providers. Major tech players, who are also Nvidia's largest customers, are actively diversifying their AI infrastructure. Meta announced it would utilize AMD's Instinct GPUs and Google's Tensor Processing Units, while OpenAI revealed a major commitment to Amazon's Trainium AI chips — representing 2 gigawatts of computing capacity. This strategic shift by key customers signaled a potential long-term threat to Nvidia's market dominance, overshadowing its current stellar performance and leading to a broader sell-off in the tech sector. Nvidia's guidance for the upcoming quarter was strong, calling for 77% revenue growth, but analysts see growth rates slowing materially in subsequent years.
Investment implications: The diversification of AI chip sourcing by major tech firms suggests a more competitive landscape ahead. While Nvidia remains the dominant AI chip provider, investors should monitor the progress of competitors like AMD, Google, and Amazon, as increased competition could pressure margins and market share over the long term. The current pullback may represent a buying opportunity for long-term investors, but near-term volatility is likely to persist.
Hotter Inflation Data Fuels Fed Rate-Hold Expectations
The January Producer Price Index (PPI) came in hotter than anticipated, rising 0.5% month-over-month against expectations of 0.3%. On an annual basis, PPI rose to 2.9%. Core PPI, which excludes food and energy, surged 0.8% month-over-month and 3.6% year-over-year, well above the 3.0% consensus estimate. This data pointed to persistent inflationary pressures within the economy, dampening hopes that the Federal Reserve would begin cutting interest rates in the near future. The inflation reading, coupled with a still-resilient labor market, gives the Fed more reason to maintain its current policy stance to ensure inflation is brought back to its 2% target range. The bond market reacted with some volatility, though Treasury yields ultimately fell as growth concerns outweighed the inflation data.
Investment implications: Persistent inflation and a patient Fed could create headwinds for equities, particularly growth stocks that are more sensitive to interest rate changes. Investors may consider increasing exposure to value stocks and sectors that tend to perform better in an inflationary environment, such as Energy and Materials, while being cautious about duration risk in fixed income portfolios.
Bank Stocks Tumble on AI Disruption and Credit Concerns
The financial sector experienced a sharp sell-off on Friday, with the KBW Nasdaq Bank Index falling approximately 4.9% — its worst day in months. The decline was attributed to a dual threat: the disruptive potential of AI on the financial services industry and renewed concerns about credit quality. The uncertainty surrounding AI's impact on jobs and economic stability, combined with specific credit issues at some financial technology companies, created a risk-off sentiment that weighed heavily on bank shares. Asset managers and brokerage firms were also caught in the downdraft, as investors reassessed the impact of AI-driven automation on the profitability of traditional financial services.
Investment implications: The financial sector faces uncertainty from both technological disruption and the credit cycle. Investors should be selective, focusing on banks with strong balance sheets, diversified business models, and a clear strategy for navigating the evolving technological landscape. The sector's underperformance year-to-date (-6.79%) may offer value for patient investors with a longer time horizon.
Sector Performance Analysis
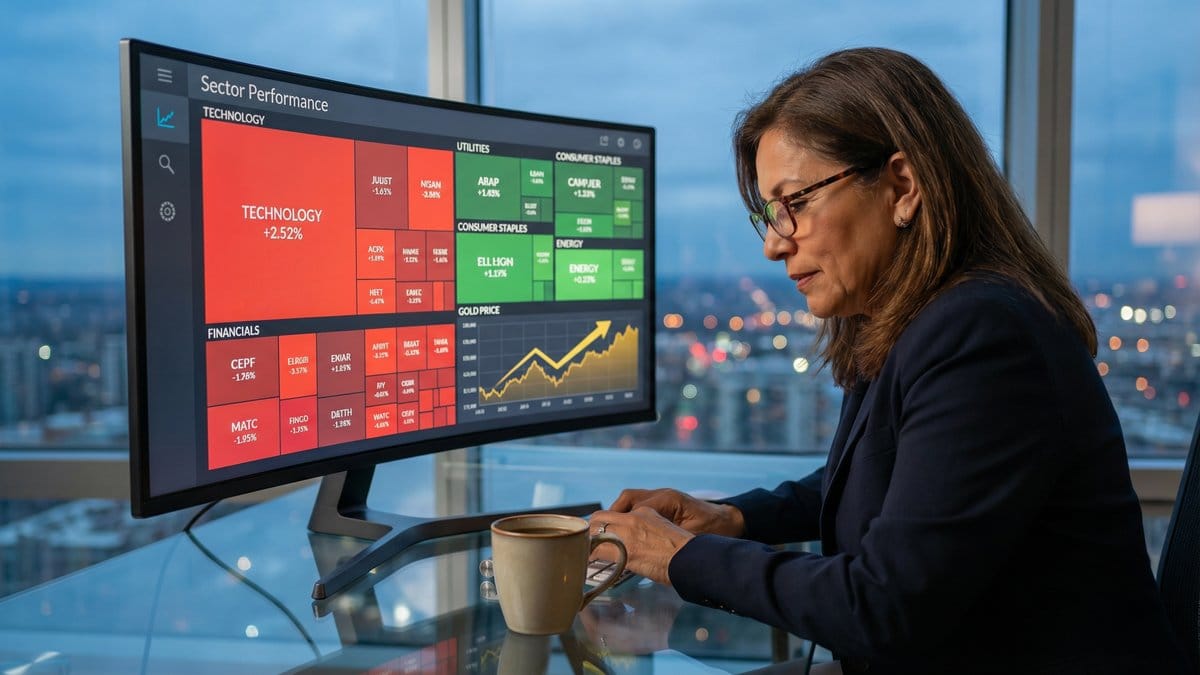
The week's market turmoil resulted in a clear divergence in sector performance, with a pronounced rotation from growth-oriented sectors into defensive areas of the market. The Financials sector (-2.43%) and Information Technology (-2.15%) were the worst performers, directly impacted by the concerns over AI competition, credit risks, and the broader risk-off sentiment. Consumer Discretionary (-0.97%) also lagged as investors grew more cautious about the consumer spending outlook.
In contrast, defensive sectors traditionally seen as safe havens during periods of uncertainty performed well. Consumer Staples (+2.59%) and Utilities (+2.53%) led the gains, as investors rotated into less economically sensitive areas of the market. The Health Care sector (+1.68%) and Energy (+1.64%) also posted solid gains. Energy was supported by rising crude oil prices, which climbed amid escalating geopolitical tensions between the U.S. and Iran. Gold also performed well, rising 2.77% for the week as safe-haven demand intensified, and silver surged an impressive 10.15%.
Investment implications: The sector rotation highlights a defensive shift in investor sentiment. The underperformance of technology and financials, which have led the market for an extended period, suggests a potential change in market leadership. Investors may consider a more balanced portfolio with exposure to defensive sectors — including Utilities, Consumer Staples, and Health Care — to mitigate risk in the current environment. The strong performance of Energy and precious metals also underscores the value of commodity exposure as a portfolio hedge.
Economic & Fed Developments
This week's economic data painted a mixed but cautionary picture for markets. The primary focus was the hotter-than-expected Producer Price Index (PPI), which indicated that inflation remains a persistent challenge for policymakers. This data point reinforces the Federal Reserve's cautious approach to monetary policy, making significant rate cuts in the immediate future less likely. Fed Governor Christopher Waller noted this week that the Supreme Court's recent tariff ruling had little effect on the rate outlook, signaling that the central bank remains focused on its inflation mandate.
Consumer confidence saw a slight rebound in February, with consumers reporting more plentiful employment opportunities. However, the broader 14-month trend remains negative, as consumers continue to feel pessimistic about geopolitical tensions and trade uncertainty. The labor market continues to show resilience, which, while positive for the economy, adds another layer of complexity for the Fed as it balances its dual mandate. The consensus among market participants is that the Fed will hold interest rates steady at its upcoming March 17-18 meeting, awaiting more conclusive data on the direction of inflation and economic growth before considering any policy adjustments.
Looking Ahead: Week of March 2, 2026
Investors will be keenly watching a slate of important economic releases in the week ahead. The main event will be the February Non-Farm Payrolls report, scheduled for release on Friday, March 6. Economists are forecasting approximately 60,000 new jobs added, a significant moderation from the 130,000 added in January, with the unemployment rate expected to remain at 4.3%. A robust jobs report could dampen rate-cut expectations and potentially weigh on equity sentiment, while a weak print might revive hopes for Fed easing.
Earlier in the week, the ISM Manufacturing PMI (Monday, March 2) and ISM Services PMI (Wednesday, March 4) will provide a real-time read on the health of the U.S. economy. The ADP private payrolls report on Wednesday will also be watched as a precursor to Friday's jobs data. On the earnings front, chipmaker Broadcom (AVGO) is set to report its fiscal first-quarter results on Wednesday, and the market will scrutinize its results and guidance for further indications on the health of the semiconductor industry and the broader AI investment cycle. Given the market's current sensitivity to AI-related news, Broadcom's commentary on custom chip demand from hyperscalers will be particularly important for setting the tone for technology stocks heading into March.
Disclaimer: This analysis is for informational and educational purposes only and should not be considered financial advice. Past performance does not guarantee future results. Always conduct your own research and consult with a qualified financial advisor before making investment decisions.
