



Market Overview
Wall Street enters Thursday, October 22, with an earnings-driven recovery facing renewed global risk aversion. The latest completed U.S. session was Wednesday: the S&P 500 gained 0.58% to 7,757.17, the Dow rose 0.69% to 52,856.09, and the Nasdaq Composite advanced 1.05% to 26,702.86. The Russell 2000 added 0.27% to 2,781.02, showing that smaller companies participated but lagged technology-heavy benchmarks.
Reuters attributed Wednesday’s improvement to stronger results and forecasts from artificial-intelligence businesses. Super Micro’s upbeat revenue and margin outlook helped restore confidence in AI hardware, while SpaceX’s first profit as a public company attracted attention. The sector themes were therefore technology infrastructure, aerospace and consumer discretionary exposure through Tesla. Communication services also remained important as investors assessed Meta’s advertising growth against its expanding investment commitments.
That optimism was not a clean all-clear. At approximately 4:07 a.m. EDT Thursday, Yahoo Finance showed S&P futures down 1.03%, Dow futures down 0.64%, and Nasdaq futures down 1.78%. These were overnight indications, not Thursday closing returns. Asian selling and Gulf tensions underline the tension between encouraging corporate results and financing, inflation and geopolitical risks. The relatively modest small-cap advance also argues against treating Wednesday’s rally as uniformly strong across the market. Reuters market coverage; Russell 2000 quote.
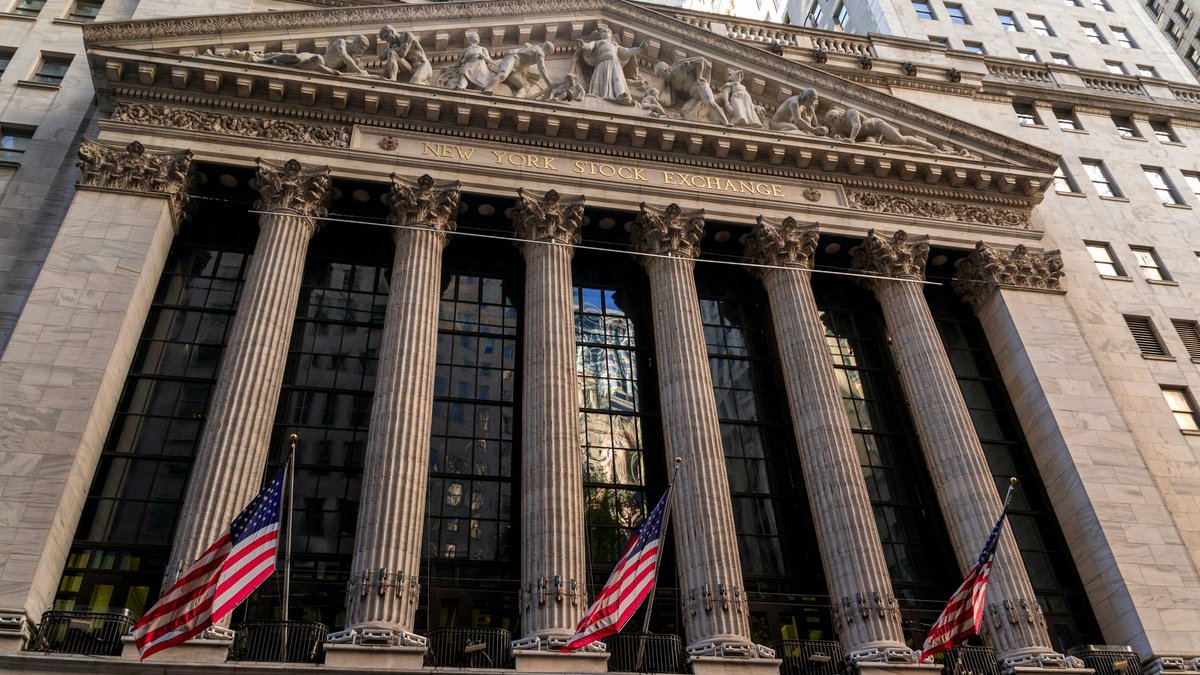
Photo: David Vives / Unsplash.
Top Market Movers
SpaceX: Earnings meet merger speculation
SpaceX closed Wednesday at $159.31, up 7.79%. Reuters connected the advance to its first reported profit as a public company and Elon Musk’s suggestion that combining SpaceX and Tesla would be a good idea. The move revived enthusiasm for the company’s AI-linked growth story, but a suggested combination is not an agreed transaction. Thursday’s early premarket quote was already below Wednesday’s close, illustrating the volatility surrounding the narrative.
Investment implications: Separate reported operating progress from speculative deal value; governance, valuation and transaction terms remain important unresolved considerations.
Tesla: Cash generation offsets investment concerns
Tesla finished Wednesday at $386.47, up 3.41%, before releasing its results after the bell. Its shareholder update reported third-quarter revenue of $28.046 billion, non-GAAP diluted earnings of $0.48 per share and free cash flow of $1.531 billion. Yahoo Finance reported that management reduced full-year capital-spending guidance to $20 billion from $25 billion. Those developments offer reassurance on funding, although quarterly operating income fell 56% year over year.
Investment implications: Improved cash generation matters, but distinguish earnings quality and automotive profitability from expectations for robotics and autonomous services.
Meta: Advertising strength, expensive expansion
Meta closed at $697.52, up 0.47%, also before its earnings announcement. Its primary release showed revenue of $64.60 billion, up 26%, and narrowed 2026 capital-expenditure guidance to $135 billion–$145 billion. It also approved non-voting Class C shares and a contingent stock dividend expected to have a two-for-one split effect.
Investment implications: Assess AI spending against future cash returns. A split changes share mechanics, not underlying business value, while voting rights deserve attention.
Economic Data & Fed Watch
The inflation-growth trade-off remains uncomfortable. September CPI, released October 14, increased 0.6% month over month and 3.7% year over year; core inflation was 2.6% annually. Gasoline accounted for more than half of the monthly headline increase. The latest available PCE report covers August, with headline inflation at 3.4% and core inflation at 3.0%. September PCE has not yet been released.
Labor demand looks less vigorous: September payrolls increased only 29,000, unemployment was 4.2%, and combined revisions lowered July and August employment gains by 60,000. September retail sales rose 0.8%, but the control-group measure advanced just 0.1%. Strong nominal spending therefore does not eliminate questions about underlying consumer momentum.
The Fed raised its target range by 25 basis points to 3.75%–4.00% on September 16; its next meeting is October 27–28. Reuters’ Thursday market report put the 10-year Treasury yield at 5.0857% and the dollar index at 101.57. For comparison, Wednesday’s official Treasury closing par yields were 4.81% at two years and 5.13% at ten years; these are different observations, not simultaneous live quotes.
Investment implications: Softer employment can support bonds, but energy-led inflation can keep policy restrictive. Rate-sensitive equities require both credible earnings and manageable refinancing needs; a single safer-haven rally does not establish a sustained decline in borrowing costs.
International Markets
Photo: Hu Chen / Unsplash.
Thursday’s Asian session reversed Wednesday’s upbeat U.S. tone. Reuters reported MSCI Asia-Pacific excluding Japan down 1.8%, the Nikkei down about 2%, South Korea down more than 4%, China’s CSI 300 down about 2%, and Hong Kong’s Hang Seng down more than 3%. Concerns over technology investment and Gulf tensions were central catalysts, highlighting how quickly confidence can weaken across interconnected markets.
Euro Stoxx 50 futures fell 0.9% in early European trading. That is a futures indication, not a verified Thursday cash-market close. Europe’s STOXX 600 had risen 0.92% Wednesday. France remained a separate pressure point: its 10-year bond yield exceeded 5%, reaching levels last seen in 2002 as economic and political concerns intensified.
Reuters quoted the euro at $1.1242 and the dollar at ¥157.55. Dollar strength and volatile energy costs can complicate conditions for emerging-market importers and companies with dollar borrowing. Regional equity losses should therefore be assessed alongside currency exposure, sovereign financing conditions and dependence on imported fuel, rather than assumed to reflect identical domestic fundamentals.
Looking Ahead
Today’s immediate U.S. economic checkpoint is initial jobless claims at 8:30 a.m. EDT. At this report’s early-morning cutoff, that release was still pending. Investors should assess whether weakness in September payrolls is appearing in higher claims, while avoiding conclusions from one volatile weekly reading. Friday brings the University of Michigan’s final consumer-sentiment report at 10:00 a.m. EDT.
Yahoo Finance’s October 22 earnings calendar lists Procter & Gamble, Union Pacific, Lockheed Martin, Blackstone, Comcast and Honeywell before the market opens. Western Digital and Newmont are among the scheduled after-close reports. Consumer pricing, transport demand, industrial orders and storage spending offer useful checks on whether earnings strength extends beyond a handful of AI-linked businesses.
Next week’s October 27–28 Fed meeting precedes October 29 releases covering the first GDP estimate and September personal income and PCE inflation. Until then, watch corporate funding plans, Treasury yields and Gulf developments together. The key test is whether earnings reassurance survives renewed pressure from energy prices and the cost of capital.
Sources
Reuters: October 21 global markets; Reuters: October 22 global markets; Yahoo Finance: early-morning market snapshot; SpaceX price; Yahoo Finance: Tesla results and price; Yahoo Finance: Meta price and earnings coverage; Tesla: primary shareholder update; Meta: primary earnings release.
BLS: CPI; BLS: employment; BEA: August PCE; Reuters: September retail sales; Federal Reserve: September decision; FOMC calendar; Treasury: official daily par yields; New York Fed: economic calendar; Yahoo Finance: earnings calendar.
Disclaimer: This analysis is for informational and educational purposes only and should not be considered financial advice. Market conditions can change rapidly, and past performance does not guarantee future results. Always conduct your own research and consult with a qualified financial advisor before making investment decisions.
