



Energy Market Overview
Oil supply risks are back in focus, while U.S. natural gas faces a more comfortable storage cushion. As of October 23, 2026, the latest completed-session prices provide the clearest comparison: Brent futures settled at $113.17 a barrel and WTI at $99.47 on October 22, according to Reuters. These are futures settlements, not live physical spot quotations.
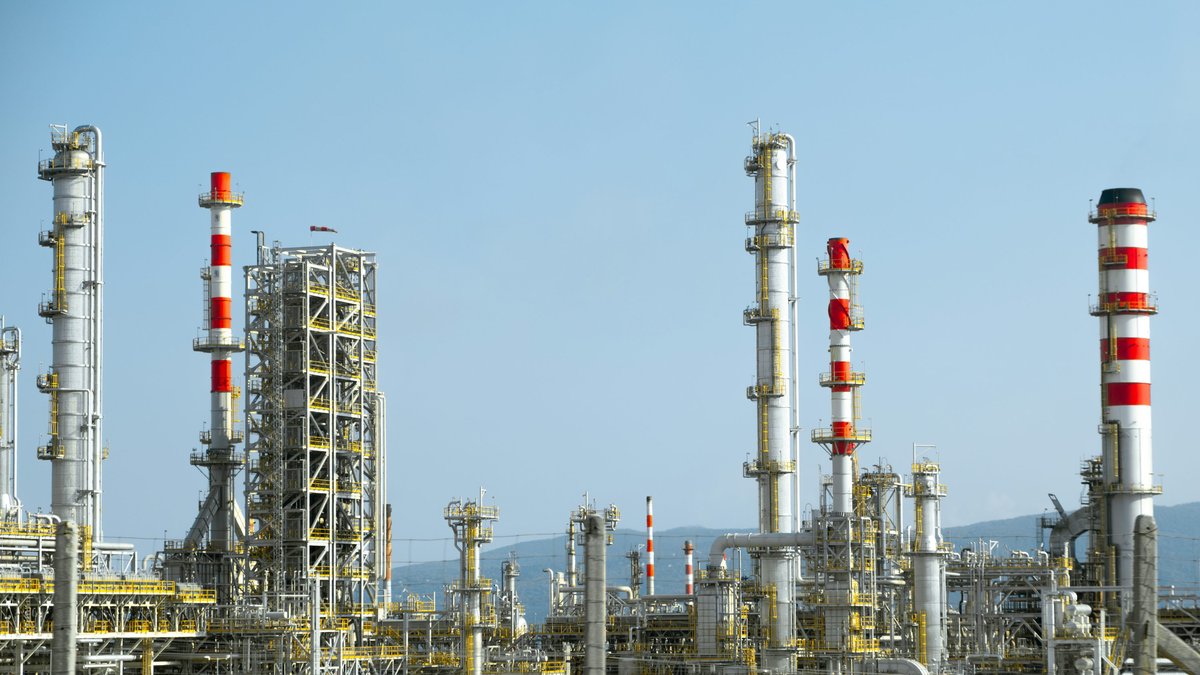
Photo: Christian Harb / Unsplash.
November Henry Hub natural gas futures settled at $2.796 per million British thermal units on October 22, based on CME settlement data. The latest published EIA Henry Hub spot assessment was $3.10 for October 20. The different instruments and observation dates matter; neither figure should be mistaken for a current intraday trading price.
The split reflects different market pressures. Crude is responding to regional security threats and disrupted supply routes. Gas investors are weighing inventories, approaching winter demand and export capacity. Renewable developers, meanwhile, face strong electricity demand but continuing financing and grid constraints.
For investors, energy is not one uniform trade. Producers, refiners, LNG operators and solar developers can react differently to the same headline. Higher oil prices may improve upstream revenue while increasing operating costs elsewhere. The central question is whether near-term disruptions translate into sustained cash generation rather than temporary commodity-price spikes.
Oil Market Analysis
Reuters attributed the October 22 oil rally to renewed regional tensions, including Houthi attacks in Saudi Arabia, alongside a Libyan pipeline-valve shutdown that reduced production. These developments raise the risk of interrupted exports and transport. They do not establish the duration of any outage, so investors should distinguish confirmed lost supply from a broader geopolitical risk premium.
The IEA’s October 14 Oil Market Report illustrates why higher prices need not mean stronger underlying consumption. It forecasts global oil demand of 102.4 million barrels a day in 2026, down 2.6 million from 2025. That is a forecast, not a final annual outcome. September supply was estimated at 102.3 million barrels a day, recovering 2.5 million from August despite continuing disruption.
Inventories remain important. The IEA reported a September decline of 10 million barrels in observed stocks, leaving them 509 million below end-February levels. Separately, the EIA’s October 21 weekly release showed U.S. commercial crude inventories, excluding the Strategic Petroleum Reserve, falling 3.1 million barrels to 412.5 million in the week ended October 16. These measures cover different markets and should not be combined as one stock total.
OPEC+ is another supply variable. On October 4, seven participating countries maintained September required production levels for November, with another review scheduled for November 1. Targets are not identical to actual production: compliance and operational interruptions still determine physical availability.
Refining also deserves attention. EIA reported U.S. refinery utilization of 93.4%, with crude inputs averaging 16.6 million barrels daily. Strong throughput can support product availability, but earnings depend on the spread between fuel prices and crude costs, not throughput alone.
Investment implications: Favor analysis of operating costs, balance-sheet resilience and exposure to disrupted regions over simply extrapolating the oil rally. Integrated companies offer several earnings drivers, while concentrated producers generally retain greater commodity sensitivity. Monitor inventory releases and realized margins before assuming elevated benchmark prices will persist.
Natural Gas & LNG
The latest EIA storage report, released October 22, recorded a 77-billion-cubic-foot injection for the week ended October 16. Lower-48 working gas reached 3,644 Bcf. Stocks were 4.0% below a year earlier but 1.0% above the 2021–2025 five-year average. That provides a modest domestic seasonal buffer, not evidence that winter supply risks have disappeared.
Weather can quickly change the balance. Heating demand increases withdrawals, while mild conditions allow inventories to last longer. EIA’s October outlook assumed winter heating-degree days nearly unchanged from last year. That is a dated seasonal assumption, not a fresh October 23 weather forecast; new forecasts and production trends remain essential signals.
LNG links domestic gas to overseas demand. Reuters reported preliminary LSEG estimates of September U.S. LNG exports at 10.9 million metric tons, versus 10.7 million in August, with Europe taking 54%. Those monthly figures establish recent context, not current terminal feedgas flows. Maintenance or unplanned outages can temporarily loosen the domestic balance.
Investment implications: Separate gas-price exposure from LNG infrastructure economics. Producers face winter weather and realized-price risk; export and pipeline businesses depend on contracts, utilization and execution. Assess debt, hedging and customer commitments rather than treating growing export volumes as a guaranteed equity return.
Renewable Energy & Transition
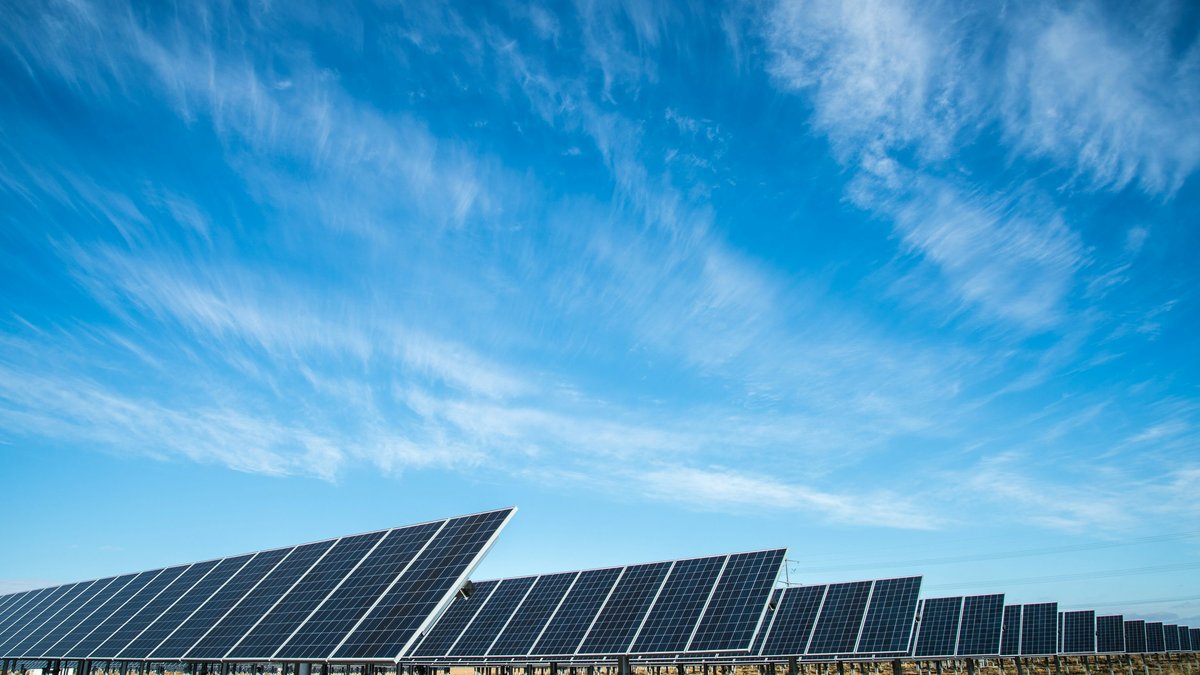
Photo: American Public Power Association / Unsplash.
The transition remains a substantial investment theme even as fossil-fuel markets dominate headlines. IEA estimates for 2025 put renewable capacity additions at roughly 800 gigawatts, including more than 600 GW of solar and around 160 GW of wind. These are historical installation estimates, not announcements of new October projects.
Demand supports the longer-term opportunity. The IEA’s Electricity 2026 outlook forecasts global electricity consumption growth averaging 3.6% annually through 2030. Solar supplies a large share of projected additional renewable generation. Wind remains important, although construction schedules, local approvals and project economics can produce uneven development.
In its October 6 outlook, EIA forecasts solar supplying 8% of U.S. electricity generation in 2026 and 9% in 2027; wind’s expected share rises from 11% to 12%. These are generation forecasts, not capacity shares or guaranteed outcomes.
Grid access is a critical constraint. The IEA identifies more than 2,500 GW in worldwide connection queues. Delays can defer revenue even when equipment is ready.
Investment implications: Examine interconnection status, financing costs, contracted power prices and execution risk. Installation growth does not automatically translate into manufacturer profits. Developers with deliverable grid connections and sustainable funding may be better positioned than businesses relying primarily on ambitious project pipelines.
Energy Stocks & Outlook
Commodity strength does not guarantee uniform share-price gains. ConocoPhillips’ investor page quoted COP at $145.71, down $0.04 or 0.03%, at 4:10 p.m. EDT on October 22. This is a dated issuer-page quotation, not a live price. Comparable October 22 ExxonMobil and Chevron quotations were not verified, so a broad energy-stock rally is not assumed.
The latest reported financials are second-quarter results. ExxonMobil reported $14.5 billion in GAAP earnings, while Chevron reported $12.1 billion. These historical profits are not third-quarter estimates. Upcoming earnings will test whether commodity conditions, refining margins and operating execution continue supporting cash flow.
ExxonMobil and Chevron are scheduled to report on October 30; ConocoPhillips’ next earnings call is November 5. Watch production reliability, spending discipline and shareholder distributions alongside headline earnings, including dividend coverage and refinancing needs. The near-term outlook remains sensitive to geopolitical developments, gas weather revisions and renewable financing conditions rather than any single benchmark price.
Sources
EIA, IEA, OPEC, Reuters, CME Group and company investor disclosures, linked alongside the relevant facts. Prices and reporting periods are dated above; forecasts are identified separately.
Disclaimer: This analysis is for informational and educational purposes only and should not be considered financial advice. Energy sector investments carry significant commodity price volatility and geopolitical risks. Always conduct your own research and consult with a qualified financial advisor before making investment decisions.
