



Week in Review: A Historic Rally Amidst Geopolitical Relief
The stock market delivered its strongest weekly performance of 2026, driven by a wave of relief following the announcement of a fragile two-week ceasefire between the United States and Iran. The benchmark S&P 500 surged 3.6% over the five-day trading period, while the tech-heavy Nasdaq Composite led the major indices with a stellar 4.7% gain, officially exiting correction territory. The blue-chip Dow Jones Industrial Average also posted a robust 3.0% advance, moving back into positive territory for the year.
The defining theme of the week was the dramatic plunge in global energy prices. Following President Trump's agreement to suspend hostilities, crude oil prices tumbled by nearly 15%, falling well below the $100 per barrel mark. This sudden drop in energy costs provided a massive tailwind for equities, as investors grew optimistic that the easing of geopolitical tensions could mitigate the severe inflationary pressures that have plagued the economy since the conflict began in late February.
Despite the strong weekly gains, trading remained choppy, particularly on Friday, as market participants digested hotter-than-expected inflation data and awaited further developments from weekend peace talks. The juxtaposition of a soaring stock market against a backdrop of surging consumer prices and uncertain geopolitical stability underscores the complex and fragile nature of the current rally. The Morningstar US Market Index rose 3.50% on the week, with 67% of covered US-listed companies finishing in positive territory.
| Index | Weekly Return | YTD Status |
|---|---|---|
| S&P 500 | +3.6% | Off <1% |
| Nasdaq Composite | +4.7% | Off <1% |
| Dow Jones Industrial Average | +3.0% | Positive for year |
| Russell 2000 | +2.99% | Negative YTD |
Top Stories of the Week: Ceasefire, Inflation, and Banking Transitions
The most consequential event of the week was undoubtedly the U.S.-Iran ceasefire agreement announced on Tuesday, April 7. The temporary halt in hostilities immediately alleviated fears of a prolonged disruption to global oil supplies through the Strait of Hormuz. The resulting plunge in crude prices — WTI crude fell 14.68% to $95.61 per barrel — sparked a broad-based rally across most equity sectors, as the market priced in a lower probability of a severe, energy-driven economic contraction. The relief was palpable: the S&P 500 surpassed its 200-day moving average for the first time since the conflict began.
However, the economic data released later in the week painted a stark picture of the war's initial impact. The Consumer Price Index (CPI) for March, released Friday, revealed that the annual headline inflation rate soared to 3.3%, up sharply from 2.4% in February — a two-year high. On a monthly basis, prices rose 0.9%, the largest gain since 2022. This acceleration was almost entirely driven by the energy sector, with the gasoline index spiking 21.2% over the month, accounting for nearly three-quarters of the overall CPI increase. Core CPI (excluding food and energy) rose a more modest 0.2% month-over-month and 2.6% year-over-year, suggesting that the inflationary impulse remains concentrated in energy rather than being broadly embedded across the economy.
In the corporate sphere, JPMorgan Chase made headlines by reporting record-shattering first-quarter earnings and officially naming Marianne Lake as the successor to longtime CEO Jamie Dimon. The bank posted a staggering $16.4 billion in net income on $49.2 billion in revenue — an 8% year-over-year increase — driven by strong investment banking fees and net interest income. Earnings per share of $5.42 comfortably beat the consensus estimate of $5.15, and the bank's Return on Tangible Common Equity hit 24%. The definitive succession timeline, which sees Lake taking the helm in January 2027, removed a significant overhang of uncertainty for the financial giant, sending JPM shares surging 4.2% to an all-time high.
University of Michigan consumer sentiment data also weighed on the mood, with the index slumping to an all-time low of 47.6 in early April, down from 53.3 in March, as persistent inflation concerns eroded household confidence. This reading, the weakest on record, underscores the disconnect between Wall Street's optimism and Main Street's anxiety.
Investment implications: The market's euphoric reaction to the ceasefire highlights the extreme sensitivity of equities to energy prices and geopolitical risk. While the immediate relief rally is encouraging, the underlying inflation data suggests that the economic damage from the recent energy shock is already embedded in the system. The hot CPI print significantly complicates the Federal Reserve's path forward, reducing the probability of near-term rate cuts. Investors should remain cautious, as the durability of this rally depends heavily on the successful negotiation of a longer-lasting peace agreement and the subsequent stabilization of oil markets. The record-low consumer sentiment reading is a warning sign that should not be dismissed.
Sector Performance Analysis: Industrials Lead as Energy Retreats
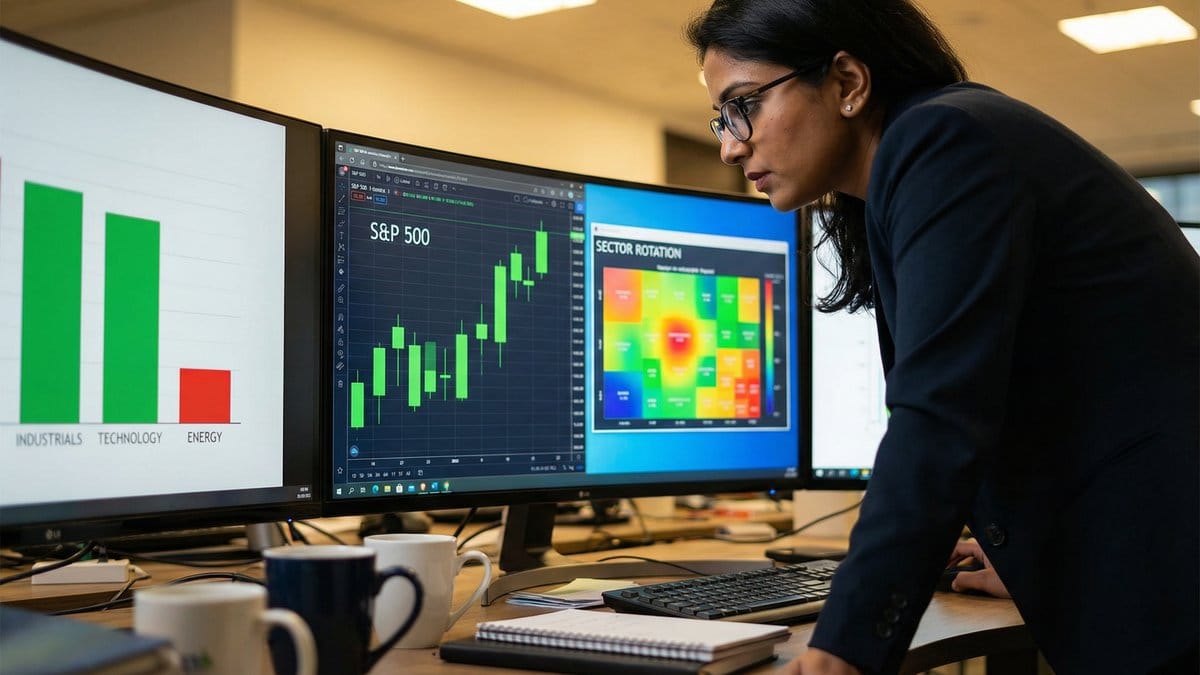
The sector performance for the week perfectly mirrored the macroeconomic narrative, with a sharp rotation out of energy and into cyclical and growth-oriented areas of the market. The Industrials sector was the standout performer, surging 5.60% as lower fuel costs and improved economic sentiment boosted the outlook for manufacturing and transportation companies. The Consumer Cyclical sector followed closely behind, gaining 5.50%, as investors bet that the drop in gas prices would provide immediate relief to consumer wallets and discretionary spending power.
Technology stocks also enjoyed a massive resurgence, propelling the Nasdaq higher. Companies like Intel surged nearly 24% on the week, while emerging AI infrastructure players CoreWeave and Nebius Group posted gains of 24% and 33% respectively. The tech sector's outperformance reflects a renewed appetite for risk and a belief that lower energy costs will support continued investment in digital infrastructure and artificial intelligence. Communication Services also posted solid gains of approximately 5.76% for the week.
Conversely, the Energy sector was the clear laggard, dropping 3.77% for the week. The sudden plunge in crude oil prices triggered a wave of profit-taking in oil and gas stocks, which had previously been the market's primary safe haven during the conflict — and remain up over 38% year-to-date. The Healthcare sector also underperformed, edging up a mere 0.25%, as investors rotated out of defensive positions and into higher-beta assets. Consumer Staples was the worst-performing sector for the period, declining approximately 1.4%.
| Sector | Weekly Return | Notable |
|---|---|---|
| Industrials | +5.60% | Best performer |
| Consumer Cyclical | +5.50% | Strong gains |
| Communication Services | +5.76% | Strong gains |
| Technology | Strong gains | Intel +24%, AI names led |
| Healthcare | +0.25% | Underperformed |
| Consumer Staples | -1.4% | Worst performer |
| Energy | -3.77% | Oil price plunge |
Investment implications: The sharp reversal in sector leadership underscores the importance of remaining agile in a headline-driven market. While the Energy sector's pullback presents a potential buying opportunity for long-term investors who believe oil prices will remain structurally elevated, the immediate momentum clearly favors cyclical and technology stocks. A balanced portfolio approach, combining exposure to secular growth themes like AI infrastructure with defensive hedges against renewed geopolitical volatility, remains the most prudent strategy. Investors should also note the significant divergence within the technology sector itself, where AI-adjacent hardware names are thriving while many software companies continue to struggle amid concerns about AI disruption to their business models.
Economic & Fed Developments: Inflation Complicates the Rate Cut Narrative
The March CPI report severely complicated the Federal Reserve's monetary policy outlook. While the central bank held its benchmark interest rate steady in the 3.50%–3.75% range at its March meeting, the minutes released this week revealed a growing openness among policymakers to potential rate hikes if inflation proved stickier than expected. The subsequent release of the 3.3% headline inflation figure validated those concerns, with the monthly 0.9% gain representing the sharpest single-month acceleration since 2022.
The surge in energy-driven inflation has forced the market to rapidly reassess its expectations for rate cuts in 2026. Prior to the ceasefire, the consensus view was that the Fed would remain on hold for the foreseeable future. While the temporary truce has revived some hopes for a late-year cut, prominent voices on Wall Street, including JPMorgan's chief economist, are now warning that the Fed may not cut rates at all in 2026, and could even be forced to hike in 2027 if the energy shock leads to entrenched stagflation. The 10-year Treasury yield fell modestly to 4.31% from 4.35% on the week, while the 2-year yield eased to 3.81%, reflecting a slight improvement in the near-term growth outlook following the ceasefire. Gold prices rose 1.59% to $4,746.50 per ounce, reflecting continued demand for inflation hedges.
Looking Ahead: Earnings Season Takes Center Stage
As the market looks to the week of April 13, the focus will shift decisively from macroeconomic data to corporate fundamentals, with the first-quarter earnings season kicking into high gear. The financial sector will dominate the early part of the week, with major reports expected from BlackRock and JPMorgan Chase on Tuesday, followed by Bank of America, Wells Fargo, Citigroup, and Goldman Sachs in the days that follow. Investors will be scrutinizing these results for signs of stress in commercial real estate, the health of the consumer, and the impact of the recent interest rate volatility on net interest margins. Analysts broadly expect good results, with 2026 corporate profit growth estimates still in the 11–13% range.
Beyond the banks, the market will also receive key economic updates, including the March Producer Price Index (PPI) on Tuesday, the Federal Reserve's Beige Book on Wednesday, and Industrial Production and Retail Sales data later in the week. These reports will provide further clarity on the extent to which the recent energy price spike has filtered through to the broader economy. The market will also be watching closely for any updates from the ongoing U.S.-Iran peace talks, as the outcome of those negotiations will be the single most important variable for energy prices — and by extension, the inflation and rate outlook — in the weeks ahead. Ultimately, the market's ability to sustain its recent momentum will depend on whether corporate earnings can demonstrate sufficient resilience to offset the lingering headwinds of inflation and geopolitical uncertainty.
Disclaimer: This analysis is for informational and educational purposes only and should not be considered financial advice. Past performance does not guarantee future results. Always conduct your own research and consult with a qualified financial advisor before making investment decisions.
